Colorado Option plans make it easier to compare health insurance companies because they use a standardized benefit design. When you compare plans at the same metal level, the deductibles, copays, and coinsurance for most covered services are the same across insurance companies.
For example, a 2027 Colorado Option Gold plan has the same $2,400 individual deductible and $55 specialist copay whether you buy it from Anthem, Colorado Access Choice, Denver Health Elevate, Kaiser, Rocky Mountain Health Plans, or Select Health.
You focus on the differences that remain: the monthly premium, the doctors and hospitals in the network, prescription drug coverage, and customer service. Colorado Option plans are ACA-compliant coverage sold and administered by private insurance companies. They are available for individuals, families, and small businesses.
What makes Colorado Option plans great
All ACA-compliant individual and small-group plans cover essential health benefits, including hospital care, prescriptions, maternity care, and mental health treatment. Colorado Option plans add a standardized design for what you pay when you use those benefits.
For 2027, key features include:
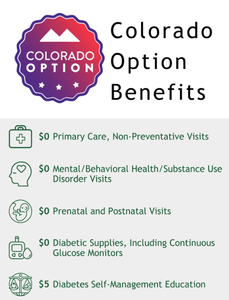
- $0 in-network primary care visits on Silver and Gold plans. Bronze plans cover the first three visits at $0. After that, the deductible applies, followed by a $50 copay.
- $0 in-network mental health and substance use disorder office visits at every metal level.
- $0 in-network prenatal and postnatal visits on Silver and Gold plans. Bronze plans cover the first three visits at $0, followed by the deductible and then a $50 copay.
- Copays for covered prescription drugs, with the amount based on the drug’s tier.
- $0 coverage for certain diabetic supplies, including continuous glucose monitors, subject to the plan’s coverage requirements.
A $0 office visit does not make every service performed during the appointment free. Lab work, imaging, procedures, and other separately billed services can have their own charges. The prenatal visit benefit also does not make labor and delivery free.
2027 Colorado Option benefits comparison
These amounts apply to covered in-network care. The Silver column shows the standard plan before income-based cost-sharing reductions.
| Benefit | Bronze | Standard Silver | Gold |
|---|---|---|---|
| Individual deductible | $8,100 | $5,000 | $2,400 |
| Individual out-of-pocket maximum | $11,200 | $11,450 | $10,450 |
| Primary care office visit | First 3 visits $0, then deductible, then $50 | $0 | $0 |
| Mental health/substance use office visit | $0 | $0 | $0 |
| Specialist office visit | 50% after deductible | $90 | $55 |
| Urgent care | 50% after deductible | $80 | $50 |
| Inpatient hospital care | 50% after deductible | 40% after deductible | 30% after deductible |
The listed Silver and Gold office visit and urgent care copays apply before you meet the deductible. Deductibles and out-of-pocket maximums are annual amounts. Family limits are higher. Premiums do not count toward the deductible or out-of-pocket maximum, and that maximum generally does not include noncovered services or out-of-network care.
The $0 mental health benefit applies to qualifying office visits. Hospital treatment and other outpatient mental health services can have deductibles and coinsurance.
The difference in metal level
Before choosing a plan, compare:
- Monthly premium: What you pay after any financial assistance.
- Provider network: Whether your doctors, hospitals, specialists, and other providers participate in that specific plan.
- Prescription coverage: Whether your medications are covered, their assigned tiers, and any prior authorization or pharmacy requirements.
- Plan rules and service: Referral requirements, claims administration, and how you get help.
For example, two Colorado Option Gold plans can have the same $2,400 individual deductible and $55 specialist copay. One might include your preferred hospital while the other does not. That difference can matter more than a modest premium difference.
Colorado Option plans are designed to improve affordability, but does not guarantee the lowest premium or lowest total cost.
Compare them with other available ACA-compliant plans. A plan with a lower premium might have a higher deductible or fewer services covered before the deductible. A higher-premium plan might save you money if you use substantial care.
Also compare the out-of-pocket maximum. In 2027, the standard Colorado Option Silver plan has a higher individual out-of-pocket maximum than the Bronze plan, even though it has a lower deductible and more generous coverage for many routine services. Metal levels alone do not tell the whole story.
Using subsidies with a Colorado Option plan
Yes. Eligible people can use premium tax credits toward Colorado Option coverage purchased through Connect for Health Colorado. Eligible households can also receive Colorado Premium Assistance.
Those programs are not exclusive to Colorado Option plans. Other eligible Marketplace plans can receive them too.
If you qualify for cost-sharing reductions, you must select an eligible Silver plan through Connect for Health Colorado to receive those extra benefits. They lower what you pay when you use your coverage.
For 2027, the Colorado Option Silver variations have these individual limits:
| Silver variation | Individual deductible | Individual out-of-pocket maximum |
|---|---|---|
| Standard Silver | $5,000 | $11,450 |
| Silver 73 | $3,400 | $9,150 |
| Silver 87 | $1,100 | $3,600 |
| Silver 94 | $200 | $2,300 |
Your eligibility determines which variation is available. If you qualify for Silver 87 or Silver 94, compare those benefits carefully before choosing a different metal level.
Read our guide to Colorado health insurance subsidies for more about premium assistance and Silver plan cost-sharing reductions.
Diabetes supplies
Colorado Option plans cover certain diabetic supplies at $0, including continuous glucose monitors. But you still need to check the insurer’s covered products, eligibility criteria, authorization rules, and required supplier or pharmacy.
Do not assume every monitor, pump, test strip, or insulin product is covered at $0. Before enrolling, confirm coverage for your specific supplies and medications with the plan.
Small Business
Colorado Option plans are available in the small-group market as well as the individual market. Insurers selling small-group coverage must offer Colorado Option plans alongside their other plans in the counties where they participate. Employers should compare premiums, employee contributions, networks, and benefits with other small-group options. Individual Marketplace subsidies do not apply to an employer’s group policy.
Enrolling
For individual and family coverage, Colorado’s 2027 open enrollment runs from November 1, 2026, through January 15, 2027. Enroll by December 15, 2026, for coverage beginning January 1, 2027. Enrollments completed from December 16 through January 15 generally begin February 1.
Outside open enrollment, you generally need a qualifying event and a special enrollment period. Small-group plans follow separate enrollment and renewal rules.
Look for “Colorado Option” in the plan name when comparing coverage. Enrollment routes depend on your circumstances. Most people seeking Marketplace financial assistance enroll through Connect for Health Colorado. People whose immigration status prevents enrollment there can explore Colorado Option coverage through Colorado Connect.