Your income for ACA health insurance subsidies isn’t necessarily your salary, take-home pay, or taxable income. Eligibility is based on your household’s modified adjusted gross income, usually called MAGI.
For many people, MAGI is the same as adjusted gross income. But there are three additions that can make a substantial difference, especially if you receive Social Security benefits.
This guide explains MAGI for marketplace premium tax credits. Use the ACA MAGI calculator below to estimate your annual household income, then read on for details about what to include. Other tax benefits and programs can use different definitions of MAGI.
Estimate your ACA household MAGI
Enter estimated annual amounts for the year you need coverage. Start with AGI, before the standard or itemized deduction. This tool estimates income for marketplace premium tax credits; it does not calculate taxes, subsidies, or Medicaid eligibility.
Optional blank fields count as $0. Calculations run in your browser; this calculator does not send or save your entries. Your result depends on your estimates and which household members’ income must be included.
See current subsidy income limits and financial assistance rules.
How to calculate MAGI for ACA subsidies
Start with your adjusted gross income (AGI) on your federal Form 1040. Then add these amounts, if they apply:
| Start with or add | What to include |
|---|---|
| Adjusted gross income | Your AGI, before the standard or itemized deduction |
| Non-taxable Social Security benefits | The portion of your Social Security benefits not already included in AGI |
| Tax-exempt interest | For example, interest from tax-exempt municipal bonds |
| Excluded foreign income | Foreign earned income and foreign housing amounts excluded or deducted under the applicable foreign-income rules |
Don’t count the same income twice. Taxable Social Security benefits and taxable interest are already included in AGI.
Supplemental Security Income (SSI) is not included. SSI is different from Social Security retirement benefits and Social Security Disability Insurance (SSDI).
If none of the three additions applies, your ACA MAGI generally equals your AGI.
A simple MAGI example
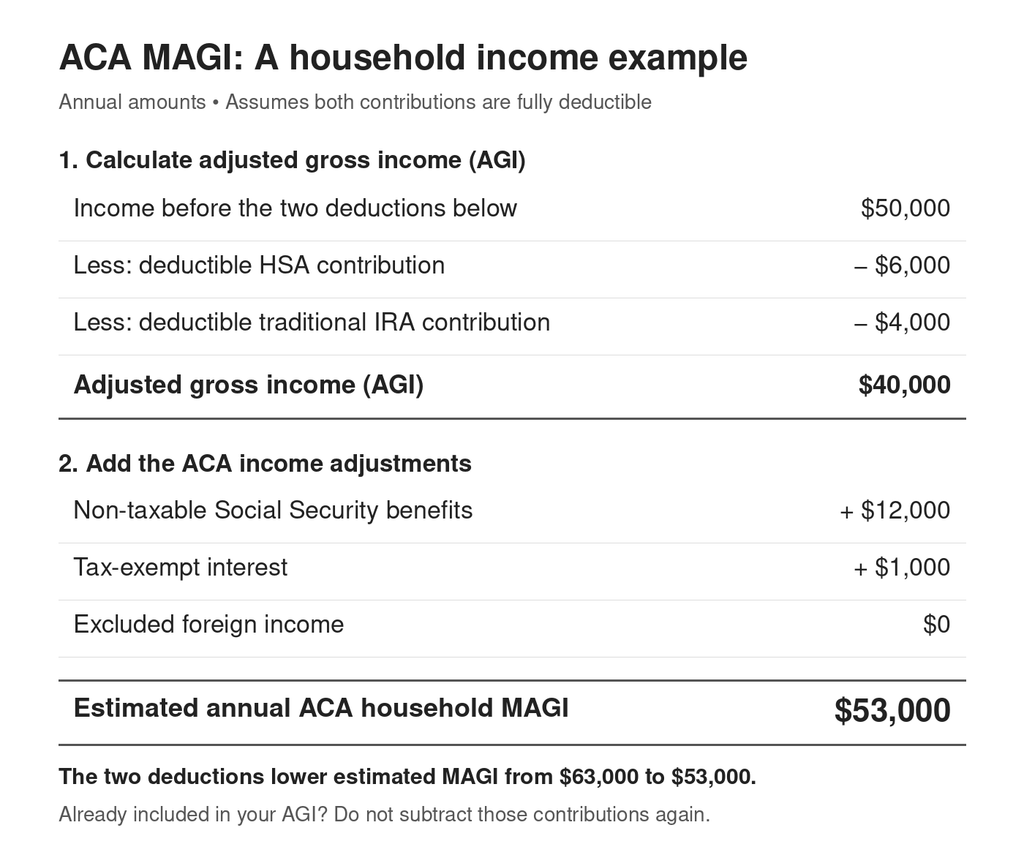
Suppose your household has $50,000 in income before these two deductions:
- $6,000 in deductible HSA contributions.
- $4,000 in deductible traditional IRA contributions.
Assuming you’re eligible to deduct both amounts in full, those contributions reduce your adjusted gross income from $50,000 to $40,000.
Now suppose your household also has:
- $12,000 in non-taxable Social Security benefits.
- $1,000 in tax-exempt interest.
- No excluded foreign income.
Adding those amounts to your $40,000 AGI produces ACA household MAGI of $53,000. Without the two deductions, it would have been $63,000.
Don’t subtract the contributions again if they’re already reflected in your AGI. Traditional IRA contributions aren’t always deductible, and HSA deductions depend on eligibility and contribution limits.
Any taxable Social Security benefits are already included in AGI. Add only the non-taxable portion.
Whose income counts?
Your marketplace household generally includes you, your spouse, and the dependents you claim on your federal tax return, even if some family members don’t need marketplace coverage.
Include a dependent’s MAGI when the dependent is required to file a federal income tax return because their income meets the applicable filing threshold. Filing voluntarily just to receive a refund doesn’t automatically mean their income counts.
For example, a spouse enrolled in Medicare can still be part of your tax household, and their income can count when determining subsidies for the rest of the family.
Estimate income for the year you need coverage
For 2027 coverage, estimate your household’s 2027 income. Your most recent tax return is a starting point, but adjust it for expected changes.
Consider changes in employment, self-employment profit, retirement distributions, investment income, and Social Security benefits. If you’re self-employed, use expected net business income after business expenses, rather than gross revenue.
A midyear retirement or job loss doesn’t erase income earned earlier in the year. Marketplace premium tax credits generally use your income for the full calendar year.
Common income-estimation mistakes
Using take-home pay. Your paycheck after withholding isn’t the figure used for subsidy eligibility.
Subtracting the standard deduction. The standard deduction and itemized deductions don’t reduce AGI or ACA MAGI.
Leaving out non-taxable Social Security. Those benefits count for ACA premium tax credits even though they aren’t subject to income tax.
Overlooking retirement withdrawals or investment gains. Taxable IRA distributions, Roth conversions, and realized capital gains can increase MAGI. Qualified Roth distributions generally don’t.
Subtracting an expense twice. If a deduction is already reflected in AGI, don’t subtract it again when calculating MAGI.
Eligible adjustments, such as deductible traditional IRA contributions and HSA contributions, can reduce AGI. Their eligibility rules and contribution limits still apply.
How MAGI affects your health insurance subsidies
Your household MAGI helps determine whether you qualify for financial assistance and how much you receive. Household size, local premiums, and other eligibility requirements also matter.
For 2027, federal premium tax credits generally end when household income exceeds 400% of the federal poverty level. Our subsidies page lists the current dollar limits and explains Colorado Premium Assistance.
Medicaid and CHP+ also use MAGI-based rules, but their household and income-period rules differ from marketplace premium tax credits. Don’t use this annual estimate alone to decide whether someone qualifies for those programs.
Update your estimate when circumstances change
Report income and household changes to Connect for Health Colorado during the year.
When you file your federal tax return, your advance premium tax credits are reconciled with the credit you actually qualify for. For 2026 and later coverage years, there is no repayment cap on excess advance premium tax credits. You must repay the full excess amount.
If your final income exceeds the subsidy income limit, you generally must repay all the advance premium tax credits received for that year.
If your income is unpredictable, you can choose to use less than your full available tax credit each month and claim any remaining credit you qualify for when you file your return.
Contact us for no-cost help comparing Colorado health insurance options and understanding how your income estimate affects financial assistance.